Lower Trucking Insurance Premiums in 2026
Trucking Insurance, Cost Savings, Owner-Operators, Small Fleets
How to Lower Your Trucking Insurance Premium in 2026
If you’re an owner-operator or run a small fleet in 2026, you’re probably feeling the squeeze. Premiums are up, freight rates are up and down, and it can feel like insurance companies hold all the cards. The truth is, you have more control than you think. With the right moves, you can lower your trucking insurance premium and keep more money in your business without cutting coverage you actually need.
Why 2026 Insurance Costs Feel So High
Across the country, small fleets are paying around $15,000 per truck per year for full coverage, and established owner-operators commonly see $9,000–$18,000+ per truck annually in premiums. Rising claim costs, repair expenses, and “nuclear verdicts” are pushing rates higher, and new authorities can pay 25–50% more in their first years (Aronson Group, LogRock data 2025–2026).
You can’t control the market, but you can control how underwriters see your operation. That’s where you win. Below are practical, real-world ways to reduce commercial truck insurance costs in 2026, based on what carriers are rewarding right now — and what we see every day at New Legacy Insurance in Greensboro, NC.
1. Protect Your MVR and CDL Like They’re Assets
Your motor vehicle record (MVR) and CDL history are the first things underwriters look at. Speeding, reckless driving, DUI, and preventable accidents are red flags that can spike your premium or get you declined altogether. One serious violation can cost you thousands of dollars per year in extra premium for several years.
- Enforce a no-tolerance policy for drugs, alcohol, and reckless driving.
- Use written driver policies and have drivers sign them, even in a 2–3-truck fleet.
- Screen MVRs before hiring and re-check them at least annually.
A clean record doesn’t just keep you legal — it’s one of the fastest ways to qualify for better trucking insurance discounts.
2. Build a Claim-Free Loss Run History
Your loss runs — typically 3–5 years of claim history — tell the story of your operation. Multiple at-fault accidents, frequent small claims, or big liability losses make you look like a bad bet, even if you’ve tightened things up recently.
To lower your trucking insurance premium long term, you want clean, boring loss runs. That means:
- Fix small damage out of pocket when it makes financial sense, instead of filing every minor claim.
- Have a written accident response plan so your drivers collect clean, accurate information on scene.
- Document corrective action after any incident — training, discipline, policy changes.
A few years of claim-free history can be the difference between a carrier walking away and a carrier competing hard for your business.
3. Install Dashcams and Capture a 5–15% Discount
Dashcams are no longer “nice to have.” They’re one of the most direct ways to earn a dashcam discount trucking insurance credit and protect yourself from false claims. Many carriers now offer 5–15% premium discounts for fleets that install and actively use dashcam systems.
- Choose cameras that record both road-facing and driver-facing views, if your drivers agree and your carrier rewards it.
- Use footage for coaching, not just punishment. Show drivers how they can avoid close calls.
In an accident, video can be the difference between a quick, low payout and a multi-million-dollar claim pinned on you. Insurers know this. That’s why they’re willing to reward you for investing in cameras.
4. Use GPS Tracking and Telematics to Prove You’re Low-Risk
GPS tracking and telematics are becoming standard. They let you monitor speed, harsh braking, idle time, and routes. More importantly, they give underwriters data that says, “This fleet takes safety seriously.”
- Share telematics reports with your agent at renewal to support your case for better pricing.
- Use alerts for speeding and hard braking and coach drivers in real time.
Some carriers directly tie telematics to trucking insurance discounts. Even when they don’t, a strong data story helps you reduce commercial truck insurance costs over time.
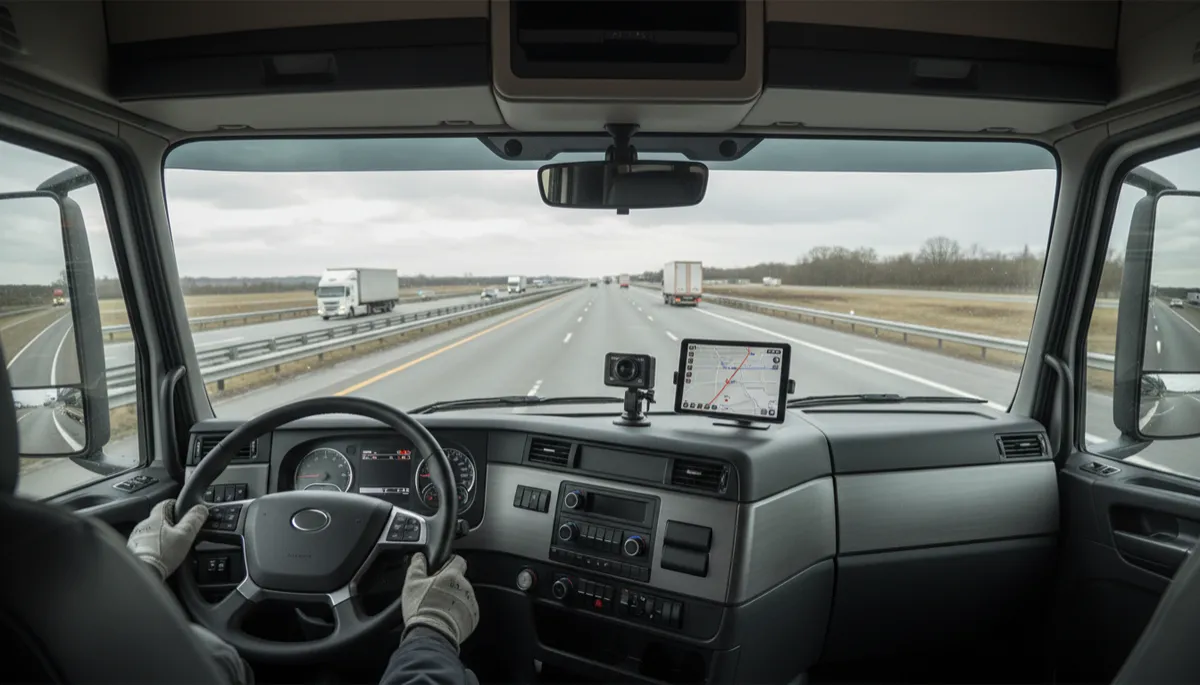
Dashcams and GPS tracking can cut premiums while protecting you from false claims.
5. Improve CSA Scores by Staying FMCSA Compliant
Your CSA score is basically your public report card. Poor scores tell insurers you ignore maintenance, hours-of-service, and safety basics. Strong scores show you run a tight ship — and that directly affects CSA score insurance pricing.
- Stay on top of preventative maintenance and document everything.
- Train drivers on pre-trip and post-trip inspections and hold them accountable.
- Take roadside violations seriously; fix root causes, not just the ticket.
Better CSA scores mean fewer headaches with DOT and better leverage when you push your agent to shop for lower rates.
6. Increase Deductibles — But Do It Strategically
One of the simplest ways to lower your trucking insurance premium is to raise your deductibles on physical damage and sometimes cargo. But this only works if you can afford to pay that deductible when something goes wrong.
- Run the math: how much do you actually save per year by moving, say, from a $1,000 to a $2,500 deductible?
- Build a reserve fund so one claim doesn’t wipe out your cash flow.
Strategic deductibles can make sense for safe fleets with strong cash management. For high-claim operations, they can backfire. This is where a good agent earns their keep.
7. Bundle Coverages with One Carrier When It Pays Off
Many insurers offer better pricing when they write your auto liability, physical damage, cargo, and general liability together. Bundling can simplify billing, speed up claims, and unlock additional credits.
- Ask your agent to compare “all-in-one” quotes with split-carrier setups.
- Make sure the bundle doesn’t hide weak coverage limits or exclusions.
Bundling isn’t always the cheapest route, but when it is, it’s an easy way to reduce commercial truck insurance costs without extra work on your part.
8. Pay Annually Instead of Monthly When Cash Flow Allows
Many carriers charge financing fees or slightly higher rates for monthly payments. If you can pay annually or semi-annually, you often save a few percentage points — real money when you’re spending tens of thousands per year on insurance.
- Ask your agent to show you the total annual cost for monthly vs. pay-in-full.
- If full pay isn’t realistic, look at quarterly or semi-annual options.
Paying in full is not just about discounts; it also reduces the risk of cancellation if a slow month makes it hard to keep up with monthly bills.
9. Work with an Independent Agent Who Actually Shops the Market
Not all agents are the same. A captive agent represents one company. An independent trucking specialist — like New Legacy Insurance in Greensboro, NC — can quote multiple carriers that write owner-operators and 1–20 truck fleets across different risk profiles, cargo types, and regions.
- They know which markets are hungry for your kind of business this year, and which ones are pulling back.
- They can position your safety practices, telematics, and loss history in the best possible light.
In a tight 2026 market, having the right advocate can mean thousands of dollars per truck in savings — without cutting the coverage that keeps you in business after a loss.
10. Understand How Your Cargo Type Drives Your Rate
What you haul matters as much as how you haul it. Insurers price based on risk and severity. For example, hazmat can add 40–100% to your premium, oversized/overweight freight can add 15–30%, and refrigerated loads often run 10–20% higher due to spoilage exposure.
- If your operation has flexibility, consider focusing on safer, lower-risk commodities to bring your premiums down.
- Make sure your agent understands your cargo mix in detail so you’re not misclassified into a riskier category than you actually are.
Sometimes the fastest way to lower trucking insurance premium is to shift away from a small slice of high-hazard freight that’s driving your whole policy cost up.
Turn Insurance from a Cost into a Competitive Edge
In 2026, commercial trucking insurance isn’t getting cheaper on its own. But fleets that invest in safety, technology, and smart risk management are already seeing flatter renewals and better options than their competitors. Clean MVRs, claim-free loss runs, dashcams, GPS tracking, strong CSA scores, smart deductibles, bundling, and pay-in-full discounts all stack together. That’s how you reduce commercial truck insurance costs in a real, measurable way.
You don’t have to guess which levers to pull or which carriers are right for your operation. That’s where New Legacy Insurance comes in. We work every day with owner-operators and 1–20 truck fleets across North Carolina and beyond, helping them find the best combination of coverage, discounts, and long-term savings.
Ready for a Straightforward Rate Review?
If you feel like you’re overpaying, don’t wait for another renewal to hit you by surprise. Get an honest, no-pressure review of your current policy, loss runs, CSA profile, and discount opportunities. We’ll show you where you’re strong, where carriers see risk, and what you can do — right now and over the next 12–24 months — to bring your premiums down.
Call New Legacy Insurance today at (336) 777-6545 or visit newlegacyinsurance.com to schedule your free trucking insurance rate review. One call could be the first step to turning insurance from a painful expense into a competitive advantage for your trucking business.
